The order of operations on a Valley Stream bankruptcy sale
People arrive at this page worried that a bankruptcy has taken the decision away from them, and to an extent it has. That is what the filing did, and it is usually working in your favor while it does it.
What you can still do is find out what the Valley Stream house is worth, which costs nothing and commits nobody. A written figure is useful information for your attorney and for the trustee, and getting one does not require anybody's approval.
Which chapter you are in changes the answer
The two chapters put a house in quite different positions, and general advice about "selling in bankruptcy" is close to useless without knowing which one applies.
We are not going to summarize bankruptcy law on a page selling houses. Your attorney will tell you where your particular filing leaves the property, what exemptions apply, and whether a sale helps or hurts the plan. Ask that question specifically, because the answer determines whether the rest of this page is relevant to you at all.
The Valley Stream market underneath this
The median is up 8.47% year over year as of 2026-05. A firming market gives you a little room for error on price, which is worth more than it sounds when the house is not in showable condition. A $775,000 median puts Valley Stream in the band where buyers are stretching to afford the house and have nothing left for the roof. That is precisely the buyer who walks away from a property needing work, and it is why condition matters more here than the price alone suggests. The median house here goes under contract in about 33 days, which is quick for Long Island. It is also a figure that only applies to property in showable condition.
A four-bedroom on State Street. In Valley Stream, bought and paid for by us.
Why cash suits a Valley Stream court timeline
Court-approved sales run on the court's schedule, and a financed buyer is a poor fit for that. Rate locks expire, approvals go stale, and a buyer who has waited two months for a hearing frequently walks.
We are not borrowing, so there is nothing on our side that expires. We can wait for a date, and we can hold a number while the process runs. On top of that there is no appraisal contingency and no financing contingency, which removes the two most common reasons an approved sale still falls apart afterward.
The condition of the Valley Stream house does not matter to us
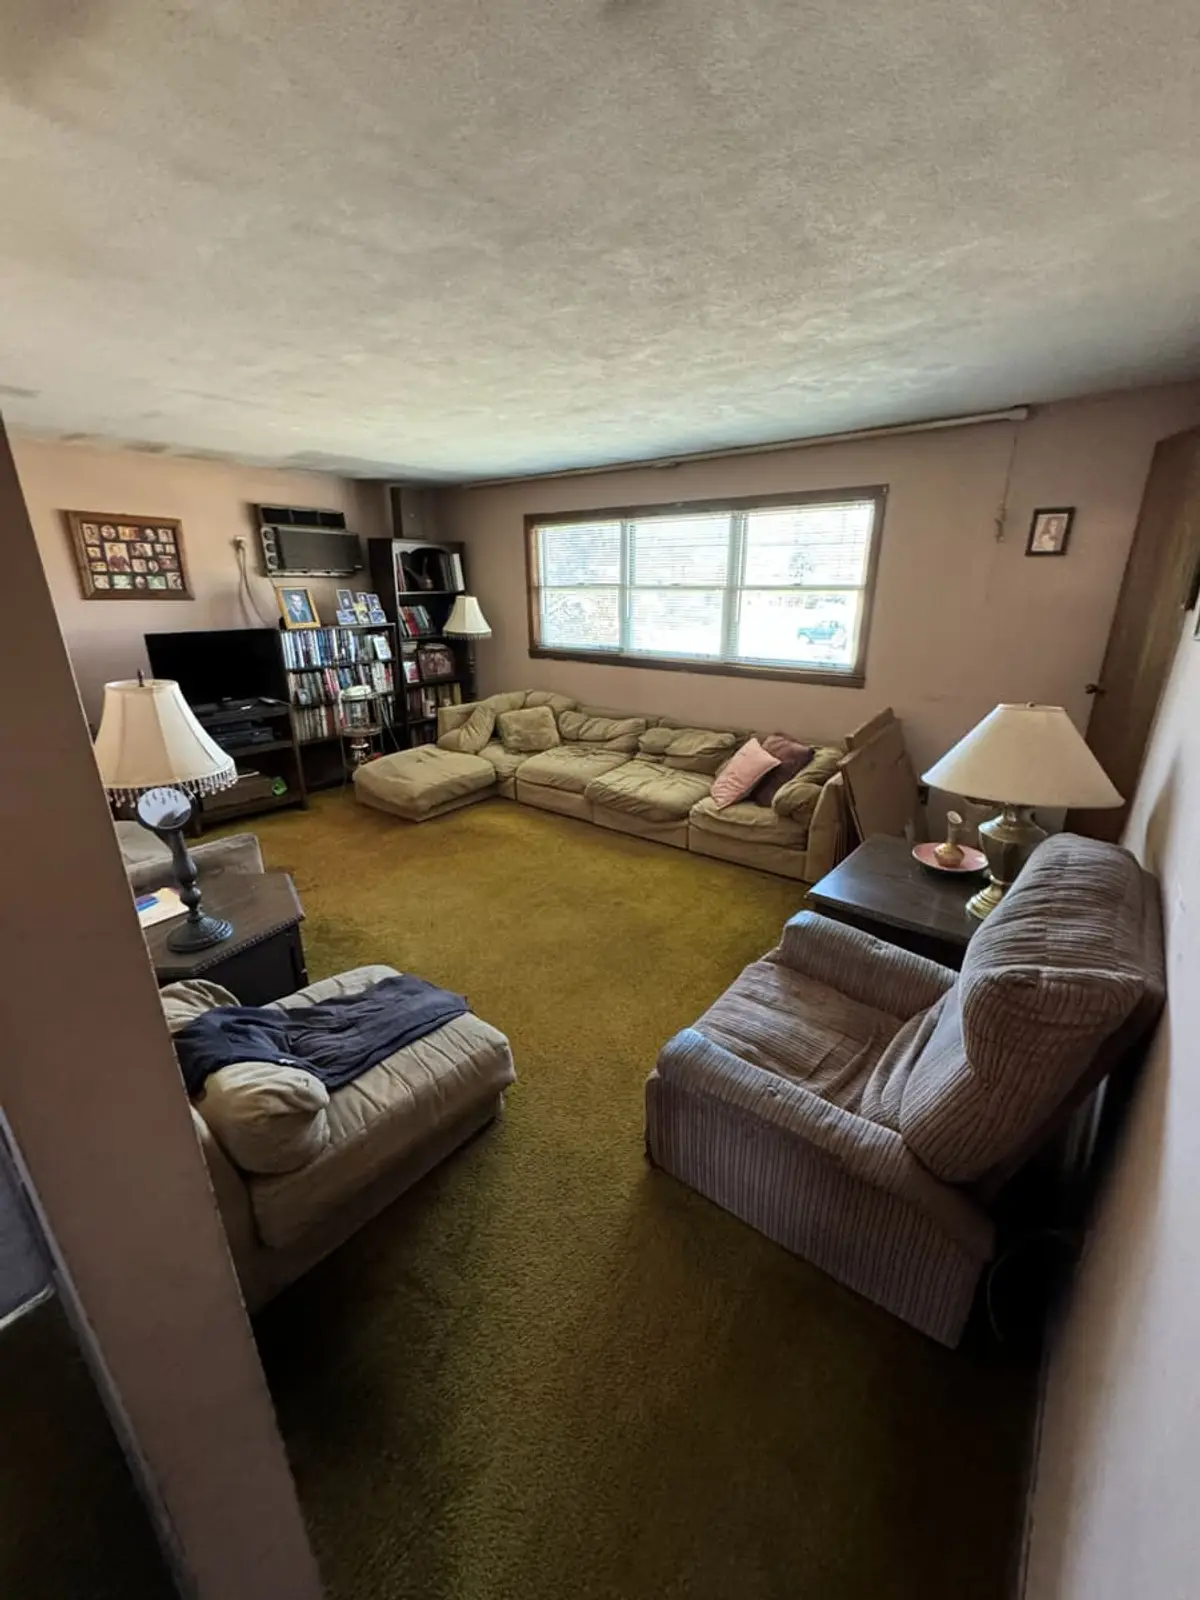
Deferred maintenance is the norm in this situation rather than the exception, and we price Nassau County houses in that condition every week. Whatever has been put off, say so at the start.
The reason to be upfront is not politeness. A number that changes after the trustee has seen it is a much bigger problem in a court-supervised sale than in a private one, and the way to avoid that is to price the house accurately the first time.
What you do not pay when you sell a house in bankruptcy
These are the costs of putting a house in bankruptcy on the market through an agent. None of them apply when you sell to us.
- Agent commission
- $38,750 at 5% of the Valley Stream median none
- Seller closing costs
- About $15,500 on a $775,000 sale. We can cover these. none
- Repairs to make it listable
- Whatever the house needs, paid up front none
- Cleanout and removal
- Paid per load, before a single buyer walks through none
- Carrying costs while it waits
- Taxes, insurance and utilities for the 78 to 93 days of finding a buyer and waiting on their mortgage none
What to bring your attorney
Your attorney will do the legal work. What slows these sales down is usually missing paperwork, and most of it is easy to gather early.
A current mortgage payoff statement from your servicer, the latest property tax bill, the deed if you have it, and our written offer with proof of funds. With those in hand your attorney can tell you quickly whether a sale fits your filing, and the trustee has what they need to look at a specific Valley Stream transaction rather than a hypothetical one.
How selling a house in bankruptcy in Valley Stream works
- 1
Tell us where it is
Just the address in 11580 and roughly what shape it is in. It takes a couple of minutes. Leave the house exactly as it is; we do not need it tidied, photographed or fixed.
- 2
One short visit
One of us comes by once, usually for less than half an hour. On a cape cod or colonial like most of Valley Stream, what we look at closely is the roof, the boiler and the wiring, not the finishes.
- 3
You get a number in writing
Within 24 hours, as a written figure rather than a range or a "starting around". Take it to a Nassau County agent for a second opinion if you want to. On a house already in showable condition, listing may well beat us, and we would rather you knew that.
- 4
The date is up to you
Close quickly, or set a date months ahead to fit probate, a tenant or your own move. Either way there is no 78 to 93 days of a Valley Stream listing looking for a buyer and waiting on a mortgage approval.
When the Valley Stream house is behind on payments too
Many people file for bankruptcy with the mortgage already behind, and some file with a foreclosure already started. The filing can change where that foreclosure stands, and your attorney will tell you exactly where yours is.
What matters for a sale is that the arrears, the mortgage and any fees all come off the proceeds at closing, like any other payoff. If there is equity in a Valley Stream house, a sale approved inside the bankruptcy can protect more of it than letting a foreclosure finish.
Common questions
Can I sell my house while in bankruptcy?
Usually it can be done, but the answer for your case comes from your bankruptcy attorney rather than from a buyer. Once you file, the house generally belongs to the bankruptcy estate, which brings in the trustee and frequently the court. Nothing should be signed until your attorney has seen it.
Do you deal with the trustee for me?
No, and be careful with any buyer who offers to. Your attorney handles the trustee and the court. We provide the offer, proof of funds, and whatever documentation is requested, then we work to the approved date.
Will you wait for court approval?
Yes, and it does not cost us anything to do so. Waiting is a problem for buyers whose mortgage approval can expire; we have no mortgage approval to lose.
Does the condition of the house matter?
No. We buy as-is, and repairs that were put off are expected here. Just as important, the number we give is the number we close at. A court-approved figure that a buyer then tries to reduce is a problem nobody needs.